 SPONSORED PARTNERMEXCExplore global spot and futures marketsEXPLORE MEXC →
 CHARTING PARTNERTradingViewAdvanced charts, indicators and market analysisOPEN CHARTS →
 TRADING PARTNERGMX via NetNapz TradeTrade decentralised perpetual marketsSTART TRADING →
TESLA · EARNINGS · AUTONOMY
Tesla Q3 Revenue Holds Near $28B as R&D Rises and Cybercab Claims Expand
Tesla’s quarterly revenue was broadly flat year over year, while operating profit fell and research spending increased. Cybercab deployment claims are company-reported and still need independent operational context.
Revenue held steady while operating income declined
Tesla reported third-quarter revenue of $28.046 billion, compared with $28.095 billion a year earlier. Operating income was $718 million, down from $1.624 billion, while net income attributable to common stockholders was $787 million and diluted earnings were $0.22 a share.
The mix matters. Automotive revenue was $20.560 billion, energy generation and storage revenue was $2.881 billion, and services and other revenue was $4.605 billion. Tesla attributed the year-on-year operating-income pressure partly to higher expenses for what it calls “SI” and other research projects, stock-based compensation and selling, general and administrative costs.
R&D and capital spending remain the key funding test
Research and development expense rose to $2.761 billion from $1.630 billion a year earlier. Tesla generated $6.263 billion of operating cash flow, spent $4.732 billion on capital expenditure and reported $1.531 billion of free cash flow. Cash, cash equivalents and short-term investments ended the quarter at $45.447 billion.
NetNapz assessment: the balance sheet gives Tesla room to fund vehicle, compute, battery and robotics projects, but the quarter does not by itself establish commercial returns from that spending. Revenue resilience should not be confused with stable profitability.
Cybercab progress is company-reported, not an audited service metric
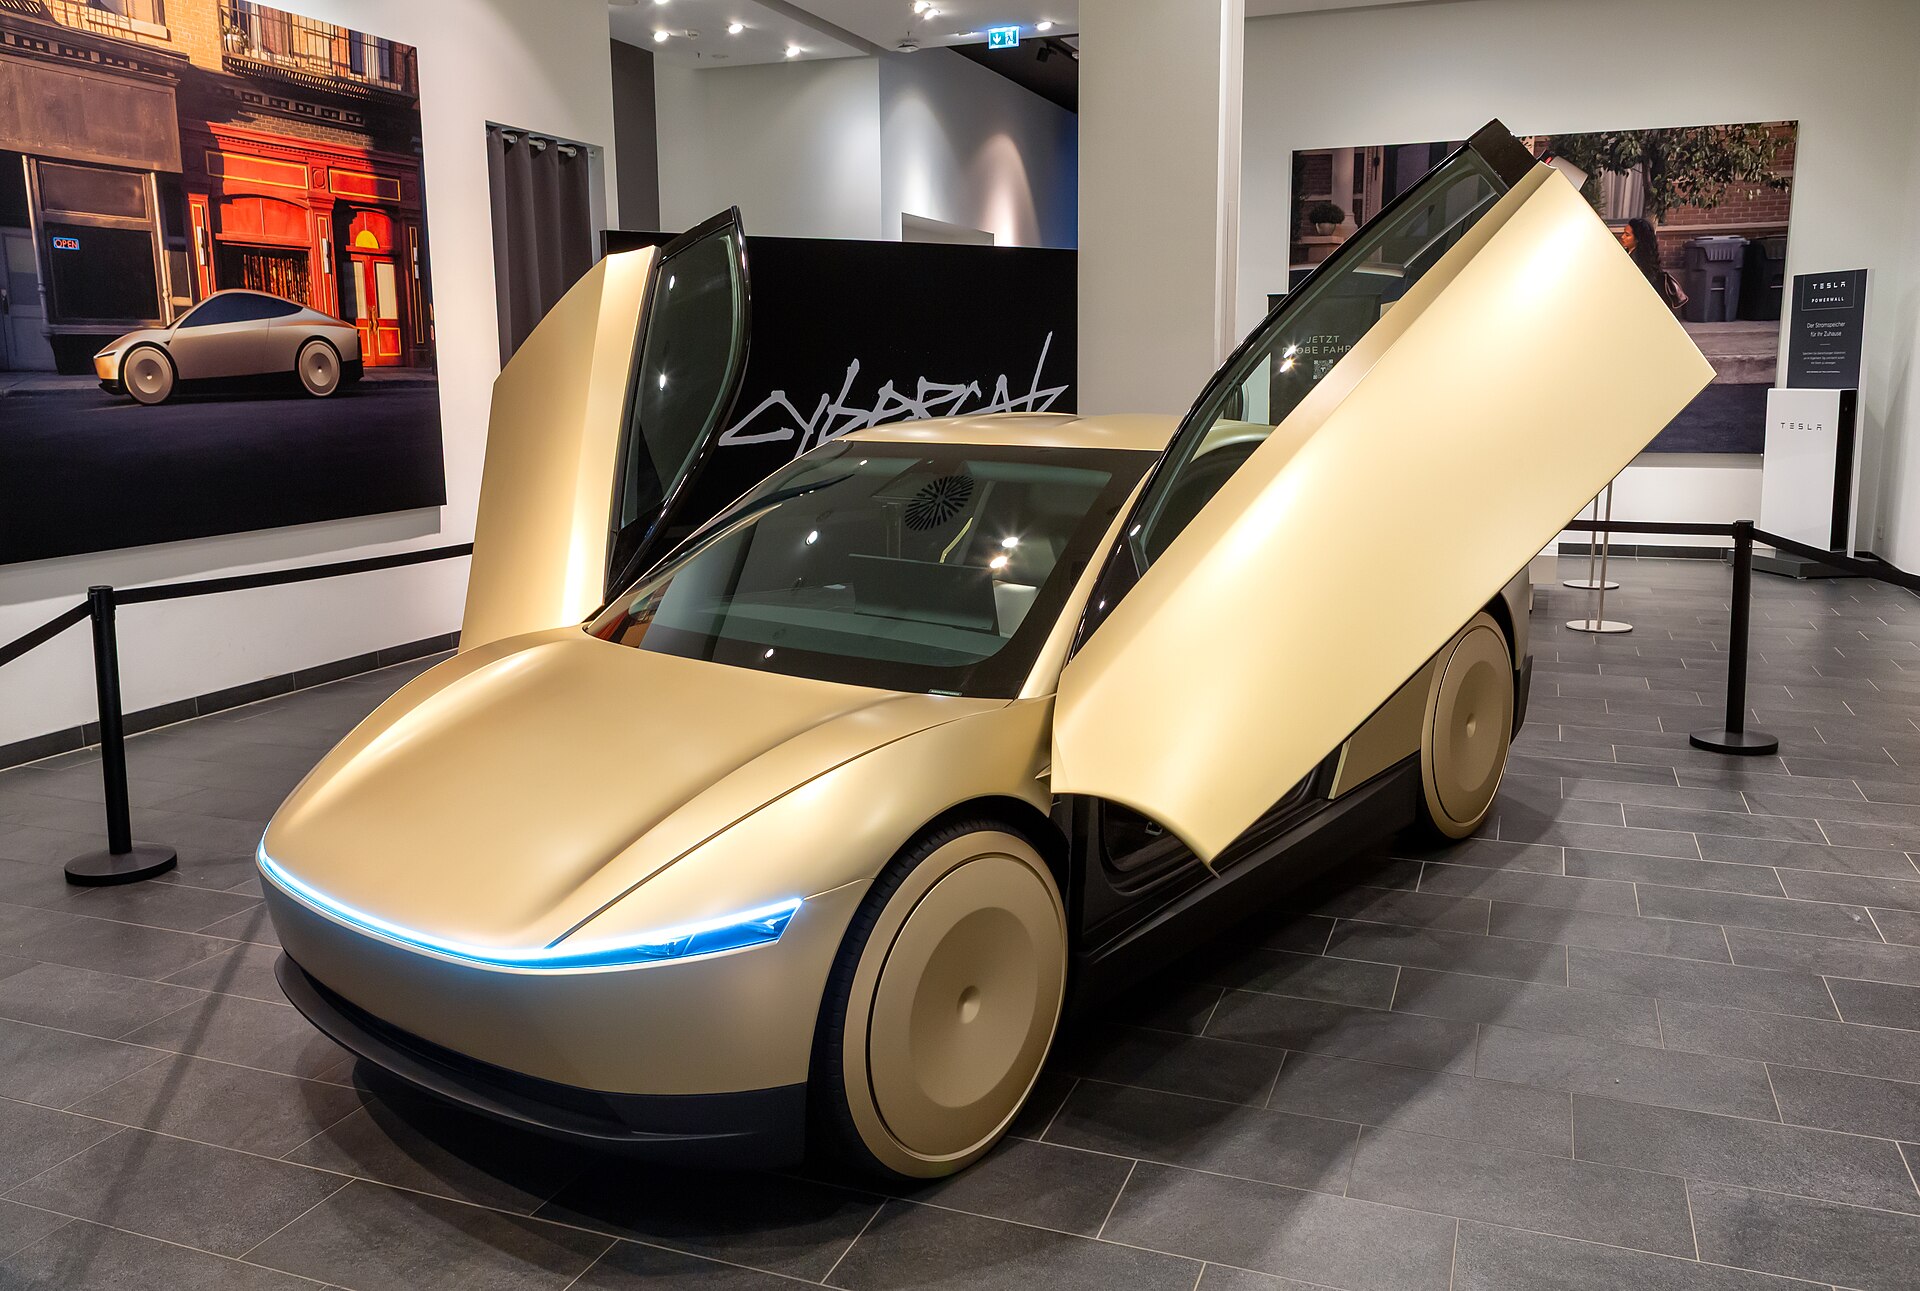
Tesla said it began deploying Cybercab into its Austin Robotaxi fleet and had reached nearly two million cumulative unsupervised miles by quarter-end. It also listed installed annual Cybercab capacity above 125,000 vehicles and described the line as in production.
Those disclosures do not provide an independently verified vehicle count, paid-ride total, intervention rate, geographic service boundary or comparable baseline for operating performance. The mileage figure therefore shows Tesla’s reported programme scale, not proof of broad commercial availability or safety performance.
Tesla separately reported 486,532 total vehicle deliveries in the quarter, down from 497,099 a year earlier, and 13.7 GWh of storage deployments.
What investors should watch
- whether operating income recovers as R&D and manufacturing programmes scale;
- the conversion of Austin Cybercab deployment into disclosed fleet, ride and service metrics;
- free-cash-flow durability as capital spending remains high;
- the split between hardware margins and the software and fleet-based profits Tesla expects.
The principal evidence is Tesla’s third-quarter 2026 shareholder deck and unaudited financial statements. Figures and operational claims above are attributed to Tesla unless otherwise stated.